The History of Bitcoin: From Digital Currency to Blockchain Revolution
Disclaimer: This article is for informational and educational purposes only and reflects the author's interpretation and analysis. It is not legal, financial, investment, tax, or regulatory advice.
Bitcoin: More Than Just Digital Money
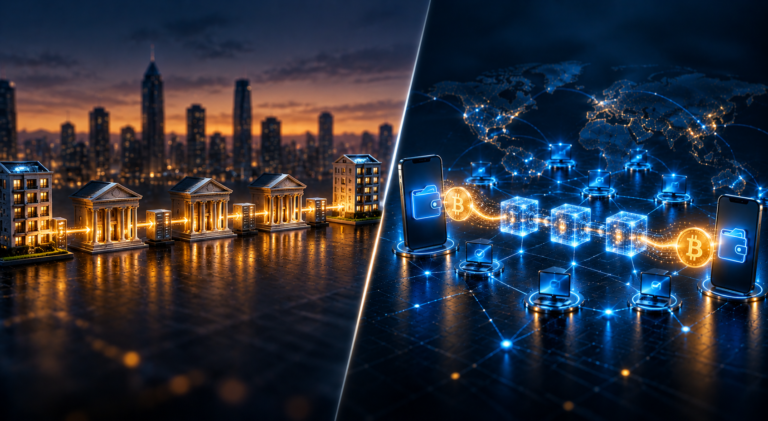
The history of Bitcoin is the story of more than just the world's first successful cryptocurrency. It's the story of how blockchain technology challenged the need for banks, governments, and other central authorities to manage digital value.
Launched in January 2009, Bitcoin introduced a radically different idea: people could transfer value over the internet directly to one another, without relying on a trusted intermediary.
But Bitcoin's significance goes far beyond digital money.
Its underlying technology, blockchain, sparked an entire ecosystem of innovation: including Ethereum, decentralized finance (DeFi), NFTs, and real-world asset tokenization, that is changing how we think about money, trust, and the internet itself.
Bitcoin was never simply about creating digital currency. It was designed to answer a much deeper question:
The answer was blockchain: a decentralized digital ledger that allows thousands of participants to agree on and record transactions without a central authority.
That breakthrough created something more important than new money.
It created a new way to establish trust.
In this article, we'll explore the history of Bitcoin: from the ideas and events that inspired its creation to Satoshi Nakamoto and the technological breakthrough that gave rise to an entirely new digital economy.
More importantly, we'll understand why Bitcoin became one of the 21st century's most significant technological innovations, and why its impact extends far beyond Bitcoin itself.
The Problem Bitcoin Was Designed to Solve
The Limitations of Traditional Digital Payments
Before Bitcoin, digital payments already existed. Billions of dollars move through the internet every day via credit cards, bank transfers, PayPal, and countless other payment systems. On the surface, these systems work fine—they're convenient, fast, and accessible.
But they all share a critical flaw: they require you to trust someone in the middle.
When you send money through a bank, you trust the bank to:
- Process your payment correctly
- Keep your account secure
- Maintain accurate records
- Not seize your funds
- Stay solvent and never collapse
When you pay with a credit card online, you trust the payment processor to handle your transaction, the merchant not to steal your information, and multiple companies not to lose your data.
This system has worked reasonably well for decades. But it comes with an inherent problem: centralized systems are vulnerable to failure, corruption, and abuse.
The 2008 Financial Crisis
In 2008, during the global financial crisis, the world witnessed the fragility of this model firsthand.
Major banks collapsed. Governments bailed out financial institutions. Millions lost their homes and life savings. Average citizens watched in disbelief as the people who caused the crisis faced virtually no consequences, while regular people paid the price through unemployment, foreclosures, and destroyed retirements.
The fundamental issue was clear: the financial system had become too centralized and too fragile. A handful of institutions made risky decisions, and when those decisions went wrong, the entire economy suffered.
This raised a critical question in the minds of cryptographers, programmers, and anyone who cared about financial freedom:
The Double-Spending Problem
Theoretically, creating digital cash without banks sounds simple. But there's a technical problem that had stumped computer scientists for decades: the double-spending problem.
With physical cash, you can only spend a dollar bill once. Once it leaves your hand, you don't have it anymore. It's impossible to spend the same physical cash twice.
But with digital money, everything is just data. Data can be copied infinitely. If you send $10 to someone digitally, what prevents you from sending the same $10 to someone else? Or a hundred other people? How do you know the digital money hasn't been copied and spent multiple times?
For decades, the only solution was to have a trusted central authority (like a bank) keep track of who owns what and prevent double-spending. The central authority had to verify every transaction and maintain the official ledger.
Then Satoshi Nakamoto solved this problem in a way that changed everything.
Satoshi Nakamoto's Breakthrough
October 31, 2008: The Bitcoin White Paper Published
On October 31, 2008—less than a month after the Lehman Brothers collapse and at the height of the global financial crisis—an anonymous person or group using the pseudonym Satoshi Nakamoto published a paper titled:
The paper was elegant in its simplicity. It was just nine pages long. But in those nine pages, Satoshi solved the double-spending problem in a way that had never been done before—and didn't require trusting anyone.
The solution had three key ingredients:
Using mathematical algorithms to create digital signatures that prove you own the Bitcoin you're sending, without revealing your private keys.
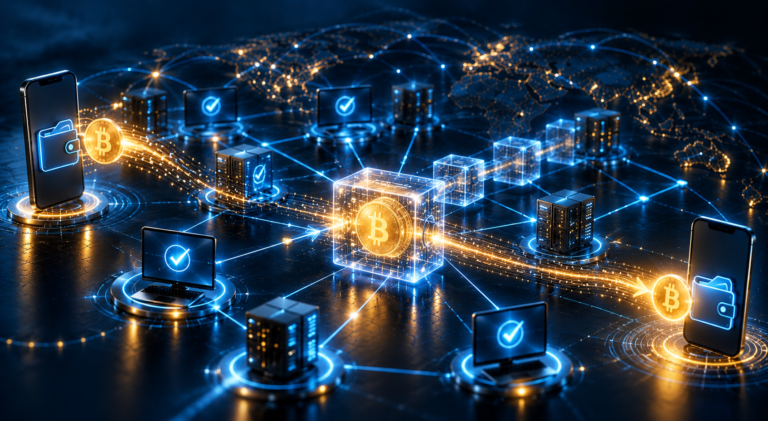
Instead of one central authority keeping the ledger, thousands of independent computers (called "nodes") would each maintain an identical copy of the transaction record.
Miners would compete to solve complex mathematical puzzles to validate transactions and add them to the blockchain. The first miner to solve the puzzle gets to add a new block and earns newly created Bitcoin as a reward.
How Bitcoin's Blockchain Technology Solved the Problem
Here's the genius of Satoshi's solution:
With thousands of nodes maintaining the exact same blockchain ledger, no single entity could cheat the system. If someone tried to spend the same Bitcoin twice:
- The first transaction would be recorded on the blockchain across nodes
- When they tried to spend it again, the network would immediately reject it because that Bitcoin was already spent
- All thousands of nodes would agree: this Bitcoin has already been transferred
January 2009: Bitcoin Goes Live
The Bitcoin Software Release: January 9, 2009
On January 9, 2009, Satoshi Nakamoto released the first version of the Bitcoin software to the public.
Anyone with a computer could download it. Anyone could join the network. Anyone could run a node and maintain a copy of the blockchain.
The architecture of Bitcoin's decentralized network was beautifully simple:
Each computer in the network ran identical software and maintained an identical copy of the entire blockchain. Because there was no central server, no single point of control, and no single point of failure, the network was virtually impossible to shut down or manipulate.
Financial Institutions need massive data centers and security teams. Bitcoin needed something different: thousands of independent participants all following the same mathematical rules.
The First Bitcoin Transaction: January 12, 2009
Only three days after the software launched, Bitcoin recorded its first real transaction—a historic moment in the history of digital currency.
Sender: Satoshi Nakamoto
Receiver: Hal Finney
Amount: 10 BTC
Hal Finney was one of the earliest developers to recognize Bitcoin's potential and became the first person besides Satoshi to receive Bitcoin. This transaction marked the beginning of the permanent, immutable blockchain—a chain that has now recorded millions of transactions and continues to grow every single day.
Think about what this moment meant: For the first time, value was transferred directly from one person to another over the internet without any bank, payment processor, or government in between.
Why Bitcoin Was Revolutionary: It created a new way to establish trust
The Problem It Solved
Before Bitcoin, every single financial system—from the most sophisticated international banking network to the simplest payment app—relied on at least one trusted central authority:
- Banks to maintain accounts and verify transactions
- Governments to regulate money and ensure stability
- Payment companies to facilitate transfers
- Clearing houses to settle transactions
Every system had a single point of control. And every system required you to trust that the institution wouldn't steal your money, freeze your account, lose your data, make disastrous decisions, or get hacked.
Bitcoin demonstrated something radically different:
The Ripple Effect: What Bitcoin Inspired
Bitcoin's breakthrough didn't just create a new form of money. It proved a technology was possible that changed everything:
- Ethereum built on Bitcoin's foundation to create programmable smart contracts, opening the door to decentralized applications.
- Decentralized Finance (DeFi) used blockchain to create lending, borrowing, and trading without banks.
- NFTs showed that blockchain could track ownership of digital and physical assets.
- Real-World Asset Tokenization is now using blockchain to tokenize real estate, commodities, stocks, and more.
All of these innovations stand on the foundation that Bitcoin created: proof that decentralized trust is possible through blockchain technology.
Conclusion: The Birth of a New Era in Finance
On October 31, 2008, in the midst of a global financial crisis, Satoshi Nakamoto published a paper proposing something radical: a form of digital money that didn't require banks.
On January 9, 2009, that idea became reality.
On January 12, 2009, the first Bitcoin transaction proved it actually worked.
Fifteen years later, the history of Bitcoin shows how it has inspired an entire industry, proven that decentralization is possible, and changed how millions of people think about money and trust.