Traditional Digital Banking Transaction vs. Bitcoin Transaction: From Initiation to Settlement
Disclaimer: This article is for informational and educational purposes only and simplifies underlying technical concepts for clarity. It is not financial, investment, or security advice.
Bank transfer vs Bitcoin transaction: on your screen, the two look almost identical. When we transfer money through a banking app, the experience appears simple.
We enter the recipient's details, enter an amount, authenticate the transaction, and press Send. Within seconds to a few business days, the money may appear in the recipient's account.
Bitcoin can provide a similar user experience: enter a Bitcoin address, specify an amount, approve the transaction, and broadcast it.
But beneath these two seemingly similar experiences lies a fundamentally different infrastructure.
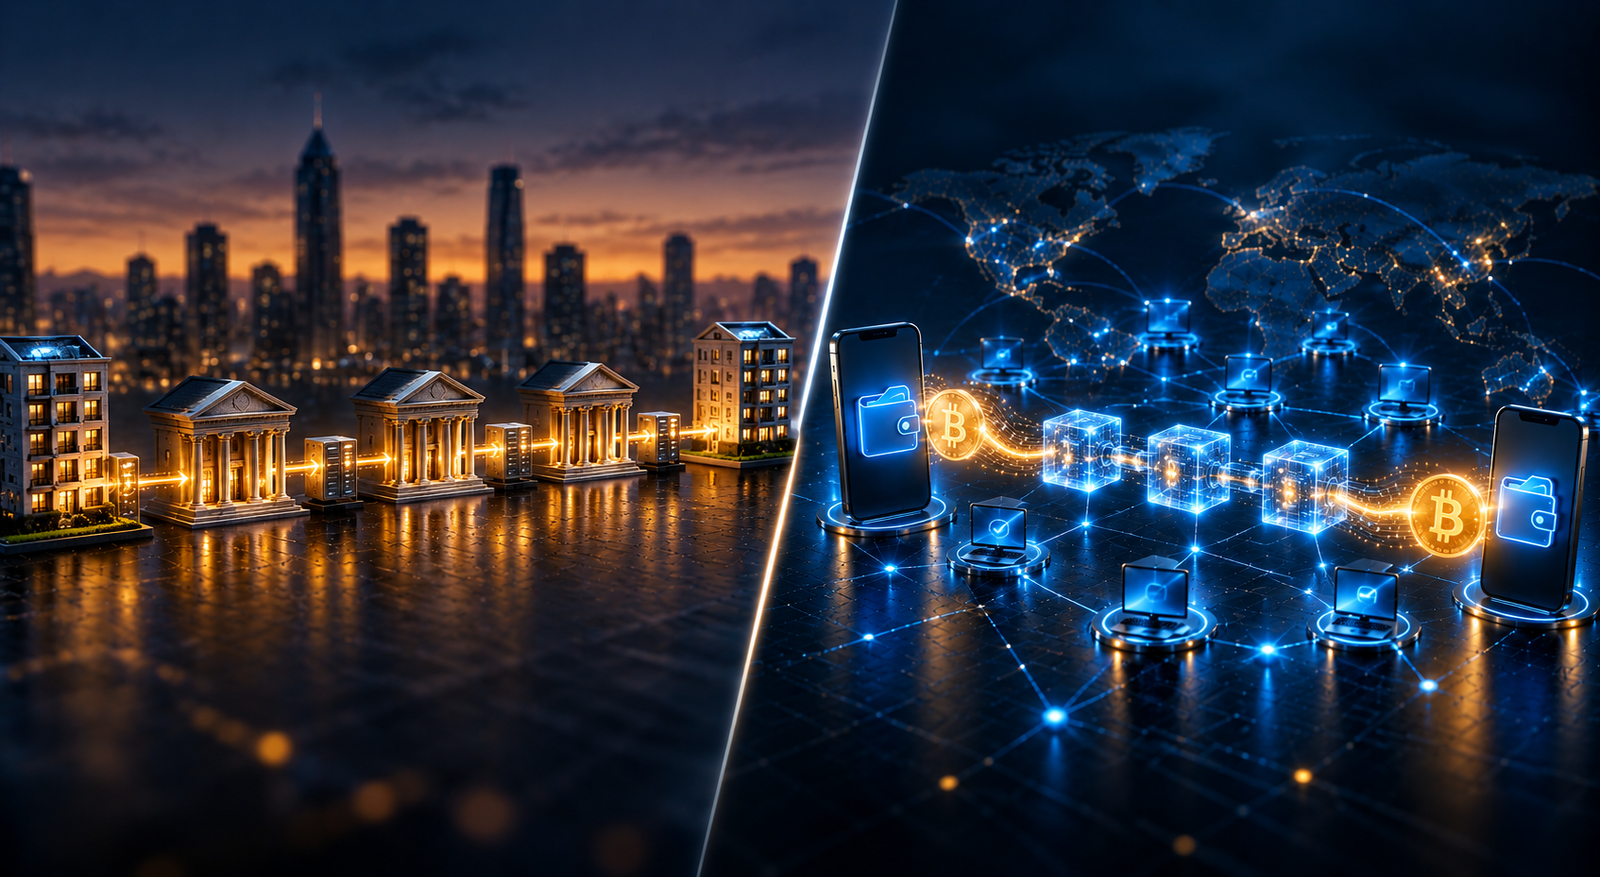
A traditional digital payment usually moves through a network of banks, payment rails, clearing systems and settlement infrastructure. A Bitcoin transaction moves through a peer-to-peer network of nodes, a mempool, miners, Proof of Work and the Bitcoin blockchain.
Let us follow both transactions from the moment they are initiated until the recipient can use the funds.
In This Article, You'll Learn
- ✓ How a bank transfer moves through validation, payment rails, clearing and settlement
- ✓ How a Bitcoin transaction is signed, broadcast, verified, mined and confirmed
- ✓ Why finality works differently in each system
- ✓ Who maintains the ledger, and what that means for trust
- ✓ The practical trade-offs between the two systems
1. The Traditional Digital Banking Transaction
Consider a simple example: you transfer $1,000 from your account at Bank A to an account at Bank B.
What you see is your banking application. Behind that simple interface, however, several systems and institutions may be involved. The simplified flow is:
Let's break this down step by step.
Step 1: Initiating the Transaction
You open your banking application and enter:
- Recipient's account details
- Recipient's bank
- Transfer amount
- Payment reference or purpose, where required
You then authenticate the transaction using mechanisms such as a password, PIN, one-time password, biometrics or multi-factor authentication.
Your banking application sends your instruction to the bank's backend systems.
Step 2: Your Bank Validates the Transaction
Your bank now performs a series of checks before allowing the payment to proceed.
- Authentication: Is the person initiating the transaction actually authorized to use the account?
- Account validation: Does your account exist and is it active?
- Balance and limit checks: Do you have enough available balance? Does the transaction exceed any daily or transaction-level limits?
- Fraud and risk checks: Does the transaction exhibit suspicious characteristics?
- Compliance checks: Depending on the payment and jurisdiction, the bank may perform sanctions, AML, or other regulatory checks.
Only after the transaction passes the relevant controls does your bank accept the payment instruction. At this point, however, the transaction may not yet be settled.
Step 3: The Payment Rail
Once your bank has validated the transaction, it needs a way to send the payment instruction to the recipient's bank. This is where the payment rail comes in.
The rail depends on the type of payment. For example:
| Transaction type | Example infrastructure |
|---|---|
| Same-bank transfer | Bank's internal systems |
| Domestic bank transfer | ACH, instant-payment or other domestic rails |
| High-value transfer | RTGS |
| Card transaction | Card networks such as Visa or Mastercard |
| International transfer | SWIFT and correspondent banking infrastructure |
For our example, the important point is simply: your bank sends the payment instruction through the appropriate payment rail to the recipient's bank. The recipient's bank can now identify the payment and the customer account to be credited.
Step 4: Clearing
Now that the payment instruction has reached the payment system, the next question is: how much does each bank owe the other?
This is the role of clearing. The clearing process takes the relevant transactions between the banks and calculates their obligations. For example, your $1,000 transfer creates an obligation for your bank to pay the recipient's bank $1,000.
In practice, a clearing system handles large numbers of payments flowing in both directions. Instead of settling every payment individually, it can net them: if, over a period, Bank A owes Bank B $1,000,000 in total and Bank B owes Bank A $800,000, only the net $200,000 needs to move.
This netting is a major reason clearing exists as a distinct function.
Step 5: Settlement
Settlement is the actual transfer of funds between the banks to discharge the obligations determined during clearing.
The banks may settle through designated settlement accounts or other settlement infrastructure, often ultimately involving central-bank money for eligible systems.
Once settlement occurs, Bank B has received the funds associated with the payment. This is the point at which the interbank obligation has actually been discharged.
Step 6: The Banks Update Their Ledgers
Bank B can now update its internal records. Conceptually:
In practice, the timing of these updates varies. Your bank typically debits your account, or places a hold on the funds, as soon as it accepts your instruction. In many systems, such as card schemes, deferred net settlement systems and many instant-payment schemes, the recipient's bank credits the recipient before interbank settlement has completed and carries a short-term exposure until settlement occurs.
Crediting the customer and settling between banks are therefore related but separate events.
Financial institutions update their ledgers and coordinate those updates through payment, clearing, and settlement infrastructure. The banking system therefore relies on a network of trusted institutions maintaining interconnected records.
2. Now Consider a Bitcoin Transaction
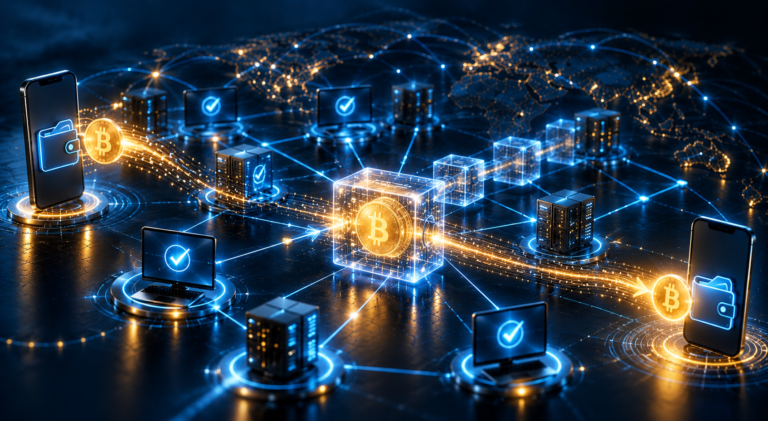
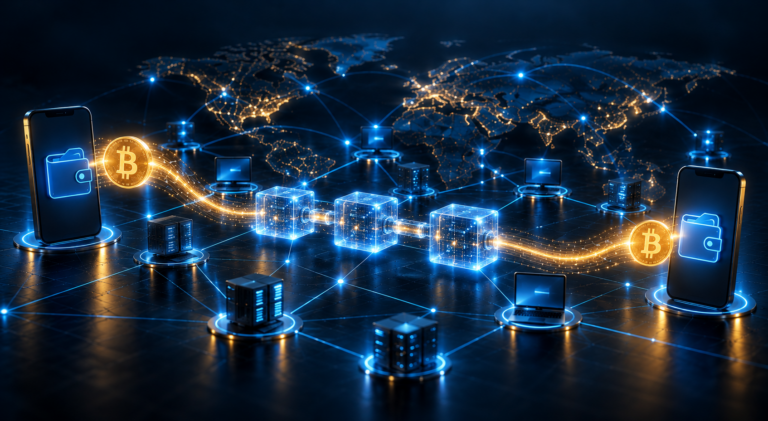
Now consider a Bitcoin transfer of 0.01 BTC from your Bitcoin wallet to another Bitcoin address. The architecture is fundamentally different. The simplified flow is:
There is:
- No Bank A
- No Bank B
- No central clearing house
- No central payment processor
- No central settlement institution
Instead, the Bitcoin protocol combines several functions that are traditionally distributed across financial institutions and payment infrastructure.
Step 1: You Create the Bitcoin Transaction
You open your Bitcoin wallet and instruct it to send 0.01 BTC to the recipient's Bitcoin address. Your wallet creates a Bitcoin transaction containing the details of the transfer.
The transaction is then digitally signed using your private key.
Step 2: The Transaction Is Broadcast
Your wallet sends the signed transaction to a Bitcoin node. The node checks the transaction.
If it considers the transaction valid, it can relay it to other nodes. Those nodes can relay it further, allowing the transaction to spread across the Bitcoin peer-to-peer network. Compare this with traditional banking:
In Bitcoin, the transaction is broadcast across the network for independent verification, rather than being sent to a single institution for processing.
Step 3: Bitcoin Nodes Validate the Transaction
Bitcoin nodes independently verify transactions according to the rules of the Bitcoin protocol. Among other things, they verify:
- Is the transaction correctly structured?
- Are the digital signatures valid?
- Are the referenced coins available to be spent?
- Does it conflict with another transaction trying to spend the same coins?
- Does the transaction satisfy the relevant spending conditions?
This is one of Bitcoin's most important characteristics. In traditional banking, the bank's systems are authoritative within the banking relationship.
Step 4: The Mempool
A valid transaction that has not yet been included in a block generally waits in a node's mempool. The mempool can be thought of as a temporary waiting area for transactions that have been validated by nodes but have not yet been included in the blockchain.
There is no single, global mempool. Each node keeps its own, and their contents can differ slightly depending on what each node has received and its local policies. When the network is busy, transactions paying low fees may wait in mempools for a long time.
Step 5: Mining and Transaction Ordering
Miners then select transactions from their mempools and compete to add the next block to the blockchain.
Because block space is limited, miners generally prioritize transactions paying the highest fee relative to their size (the fee rate). The miner of a successful block collects the fees of every transaction in it, plus newly created bitcoin (the block subsidy).
To do this, they solve a computational puzzle (Proof of Work). In practice, this means repeatedly hashing the block header with different values until the result falls below a network-defined target. The difficulty adjusts every 2,016 blocks (roughly every two weeks) so that, on average, a new block is found about every 10 minutes.
The miner that finds the solution first broadcasts the block to the network.
Step 6: The Block Is Broadcast
The new block propagates from node to node across the Bitcoin network. The nodes independently verify that the block and its transactions follow Bitcoin's rules. If the block is valid, they accept it and continue building on it.
Step 7: The Transaction Becomes Part of the Blockchain
Once your transaction is included in an accepted block, it becomes part of the Bitcoin blockchain. It is now considered confirmed.
The blockchain therefore provides the permanent, shared record of the transaction.
Step 8: Confirmations and Increasing Finality
Suppose your transaction is included in Block 900,000. It has 1 confirmation. When the next block is added, it has 2 confirmations. After another block, 3 confirmations. And so on.
The more confirmations a transaction has, the harder it becomes to reverse.
3. The Most Important Difference: Who Maintains the Ledger?
This is ultimately the heart of the comparison.
Traditional banking
The financial system consists of multiple trusted institutions maintaining their own ledgers. For example, your bank's ledger records your account balance, and the recipient's bank's ledger records the recipient's account balance.
Payment systems and settlement infrastructure coordinate the movement of value between these institutions. The system therefore depends heavily on institutional trust + legal agreements + regulated infrastructure.
Bitcoin
Bitcoin does not depend on one institution maintaining the authoritative ledger. Instead, many nodes maintain and verify copies of the blockchain. They follow the same protocol rules.
The network uses cryptography and consensus mechanisms to determine which transactions are valid and which chain represents the accepted history.
The trust model therefore shifts:
4. The Comparison at Every Layer
| Function | Traditional Banking | Bitcoin |
|---|---|---|
| Transaction initiation | Banking application | Bitcoin wallet |
| Authorization | Bank authentication mechanisms | Private-key digital signature |
| Transaction validation | Bank/payment infrastructure | Bitcoin nodes |
| Network communication | Bank/payment networks | Peer-to-peer network |
| Temporary transaction queue | Queued within the payment system's processing cycles | Mempool |
| Transaction ordering | Payment infrastructure/system rules | Miners + consensus |
| Clearing | Clearing infrastructure | No separate centralized clearing layer |
| Settlement | Settlement infrastructure | Blockchain confirmation |
| Ledger | Institutional ledgers | Distributed blockchain ledger |
| Record authority | Banks/payment institutions | Decentralized network consensus |
| Finality | Deterministic; defined by payment-system rules and law | Probabilistic; grows with confirmations/Proof of Work |
| Central intermediary | Usually present | Not required |
| Trust model | Institutions + legal framework | Cryptography + consensus |
| Fees | Set by the bank or provider; often zero for domestic transfers | Chosen by the sender; paid to miners; varies with network demand |
| Typical speed | Seconds to several business days, depending on the rail | About 10 minutes on average for the first confirmation; about an hour for 6 |
| Operating hours | Some rails run only on business days | 24/7/365 |
| Reversibility and disputes | Recalls, chargebacks and fraud recovery may be possible | No protocol-level reversal once confirmed |
| Mistakes and lost access | Bank can help recover access or trace errors | Sending to a wrong address or losing private keys usually means permanent loss |
| Identity | Accounts tied to verified identity (KYC) | Addresses are pseudonymous; KYC typically applies at exchanges |
| Capacity | Very high transaction volumes | Limited on-chain (a handful of transactions per second); layer-2 systems such as Lightning aim to add capacity |
5. The Big Conceptual Shift
The biggest innovation of Bitcoin isn't simply that it allows you to send digital money over the internet. Traditional banking already does that.
The deeper innovation is that Bitcoin attempts to create a system where digital value can be transferred and recorded without requiring a central institution to maintain the authoritative ledger and coordinate every transaction.
Traditional digital money generally looks like:
Bitcoin looks more like:
The two systems can now be placed side by side.
6. The Trade-offs
Neither system is simply "better". Each makes different trade-offs.
Traditional banking
Traditional banking offers very high capacity, consumer protections such as fraud recovery and chargebacks, the ability to correct mistakes, and a relatively stable unit of account. The cost is dependence on intermediaries, limited operating hours on some rails, access that institutions can grant or deny, and limited visibility into how ledgers are maintained.
Bitcoin
Bitcoin offers open participation, independent verification, 24/7 operation and settlement without a central operator. The cost is limited on-chain capacity, fees that rise with demand, irreversibility (including of mistakes and fraud), full personal responsibility for safeguarding private keys, and significant price volatility.
7. Conclusion
On the surface, both transactions look almost identical: enter the details, approve, send. Underneath, they answer the same question, "who keeps the record of who owns what?", in very different ways.
That is the real difference in the bank transfer vs Bitcoin transaction comparison. Traditional digital payments rely on trusted institutions that maintain separate ledgers and coordinate through payment, clearing and settlement infrastructure. Bitcoin relies on a network of independent nodes that verify every transaction against shared rules and agree on a single common ledger through Proof of Work.
Key Takeaways
- A bank transfer passes through your bank's checks, a payment rail, clearing and settlement before the interbank obligation is discharged.
- Clearing calculates what banks owe each other, often netting many payments; settlement is the actual transfer of funds between banks.
- Crediting the recipient and settling between banks are related but separate events, and their order varies by payment system.
- A Bitcoin transaction is signed with your private key, broadcast to the peer-to-peer network, verified independently by nodes and waits in mempools until a miner includes it in a block.
- Bitcoin finality is probabilistic: each additional confirmation makes a transaction harder to reverse.
- The core difference is who maintains the ledger: trusted institutions with separate ledgers, or a network of nodes agreeing on one shared ledger.